Updated for 2026: For the broader card strategy beyond Bilt, see Credit Card Rewards for Expats: Maximize Points, Miles & Cash Back (2026).
As of October 2026: Bilt relaunched the card as Bilt Card 2.0. It is issued by Column N.A. and serviced by Cardless — no longer Wells Fargo — in three tiers: Bilt Blue ($0/year), Bilt Obsidian ($95/year) and Bilt Palladium ($495/year). Rent and mortgage now earn up to 1.25X with no annual cap, and the old 5-transaction monthly minimum is gone.
This post is for you if you are paying rent in the US. As someone who rents in the Bay Area (and trust me, Bay Area rent is no joke T.T), I was pretty excited when I discovered this. For the first time in the US, you can pay rent using a credit card without paying the transaction fee (2-3%) and still earn reward points. Points transfer 1:1 to Bilt's airline and hotel partners and are valued at about 2.2 cents each by The Points Guy. Since the Bilt Card 2.0 relaunch, rent and mortgage earn up to 1.25X with no annual cap — but only to the extent you also spend on the card each cycle, so it is no longer the automatic 1X it once was (see the As of note above). I wrote about Bilt before and this post includes additional information about the card. If you think this is suitable for you, you can use this link to the Bilt Cards to apply.
(And if you prefer to listen instead of reading, you can turn the below content into podcast using DIALØGUE.)
Pros and Cons of the Bilt credit card
Pros
Cons
1. Zero fees for using Bilt credit card to pay rent
2. Wide range of rent payment options, including ACH (bank transfer) via online payment system, physical checks sent to your landlord, Venmo, Paypal
3. Up to 1.25X points on rent and mortgage payments, with no annual cap
4. Three tiers — Bilt Blue ($0/year), Bilt Obsidian ($95/year) and Bilt Palladium ($495/year)
5. Wide range of redemption options: 17 airline and 7 hotel transfer partners (24), though the card FAQ on biltrewards.com refers to "28" — plus Lyft, fitness, statement credits and even a home down payment.
6. Bilt points are valued at about 2.2 cents each by The Points Guy — among the most valuable transferable currencies
1. Rent points are no longer automatic — they now depend on how much everyday spending you put on the card
2. The top 1.25X rent multiplier needs everyday spend equal to 100%+ of your housing payment each cycle
3. The best multipliers and credits sit behind the paid Obsidian ($95) and Palladium ($495) tiers
4. Sign-up bonuses are paid in Bilt Cash rather than transferable points (except 50,000 points on the Palladium tier), so they are smaller than the cash-equivalent bonuses on some rival cards
The above is a quick summary. I will start to dive into more details below. Alternatively, if the content is too long and you want to ask some questions, you can use the chatbot that I recently built here. (This is still an experiment so be aware of hallucinations).
Is it a card for you?
Rather than giving the standard, there is no "one size fits all" answer, I will try to provide some specific comments, examples, and recommendations:
- If your main purpose is accumulating credit card reward points for travel, then you probably know that Chase and American Express are among the most popular programs. With Chase, they have the unofficial 5/24 rule so consider that. The 5/24 rule means that you will not be approved for any additional Chase personal credit card if you have opened more than five personal credit cards over the past 24 months. This is not the unofficial rule, however, and there are exceptions.
- You may want to "max" out of your desired Chase credit cards first.
- I personally got approved for another credit card from Chase after getting five personal cards in less than two years, so I know there are exceptions. And Chase changes their tactics based on market conditions.
- Bilt now offers sign-up bonuses — Bilt Cash plus 50,000 points on the Palladium tier — but if you come across a bigger cash-equivalent bonus elsewhere (like 60,000 points from Chase or 80,000 points from American Express) and want to take advantage of that first, it's fine.
- Remember that Bilt's rent rewards now depend on how much everyday spend you put on the card, so do the math to see whether Bilt or a rival card's sign-up bonus is the better first move.
- If you are an expat, who just moved to the US for less than six months, should you get a Bilt card?
- Per my previous post, your main goal should be improving your credit score. Check out eight tips to improve your credit score as expat in the US.
- You may not have many options about opening the first credit card so go ahead as best as you can. I recommend City national bank if your situation allows it. Check out this post about "Tips on how to prepare for relocation from Asia to the US", tip #3 and #4.
- Once your credit score is good to excellent and you consider between Chase and/or American Express/Capital One, then I think Bilt is a no-brainer for expat who rents. It is a good way to build your credit history too, because your rent payment is reported to the credit bureaus.
- If you worry that using credit card to pay may increase your credit utilization rate hence lowering your credit score, Bilt has the BiltProtect function, which helps you with that. Bilt does that by "pulling the full rent payment directly from a connected bank account (kind of like a debit card)". So as long as you connect a bank account to your Bilt account and have enough money for rent, it should be fine.
Rent Day: bonus rewards on the first of every month
Bilt still runs a monthly Rent Day promotion on the 1st of each month, with limited-time bonus rewards — historically extra points, transfer bonuses and sweepstakes. The exact multipliers change month to month, so check the Bilt app or biltrewards.com before planning spend around it.
What's gone is the old Bilt 1.0 rule that required at least five transactions per month to earn rent points. Under Bilt Card 2.0 there is no transaction minimum: how many points you earn on rent or mortgage depends only on which rewards option you pick (Housing-only rewards or Flexible Bilt Cash) and how much you spend on the card each cycle.
For example, with Housing-only rewards, spending 100%+ of your housing payment on everyday purchases in a cycle earns the top 1.25X multiplier on that cycle's housing payment.
My personal experience of using Bilt credit card
The notes below are from my experience with the original Bilt 1.0 card in 2023, including the old five-transaction dashboard. Bilt Card 2.0 works differently — the five-transaction requirement no longer applies — but the setup steps are broadly similar, and the screenshots show the Bilt 1.0 dashboard.
After I applied for the card, the approval was instant, and the physical card arrived after a few days. While you wait for the card, you can still set things up on the Bilt rewards website.
Bilt gave you the bank account details so you can add them to the landlord's online payment website. The setup process was straightforward, and I use the Bilt Protect function to keep my credit card utilization ratio low. Make sure that you link your checking account to Bilt so that Bilt can deduct money from there to pay for your rent.
On the Bilt website, under my account, Bilt will show you how many more transactions you need to make during the billing cycle to meet the five transaction criteria from them. For example, this is what it shows to me during the recent statement period. I need to make additional three transactions.
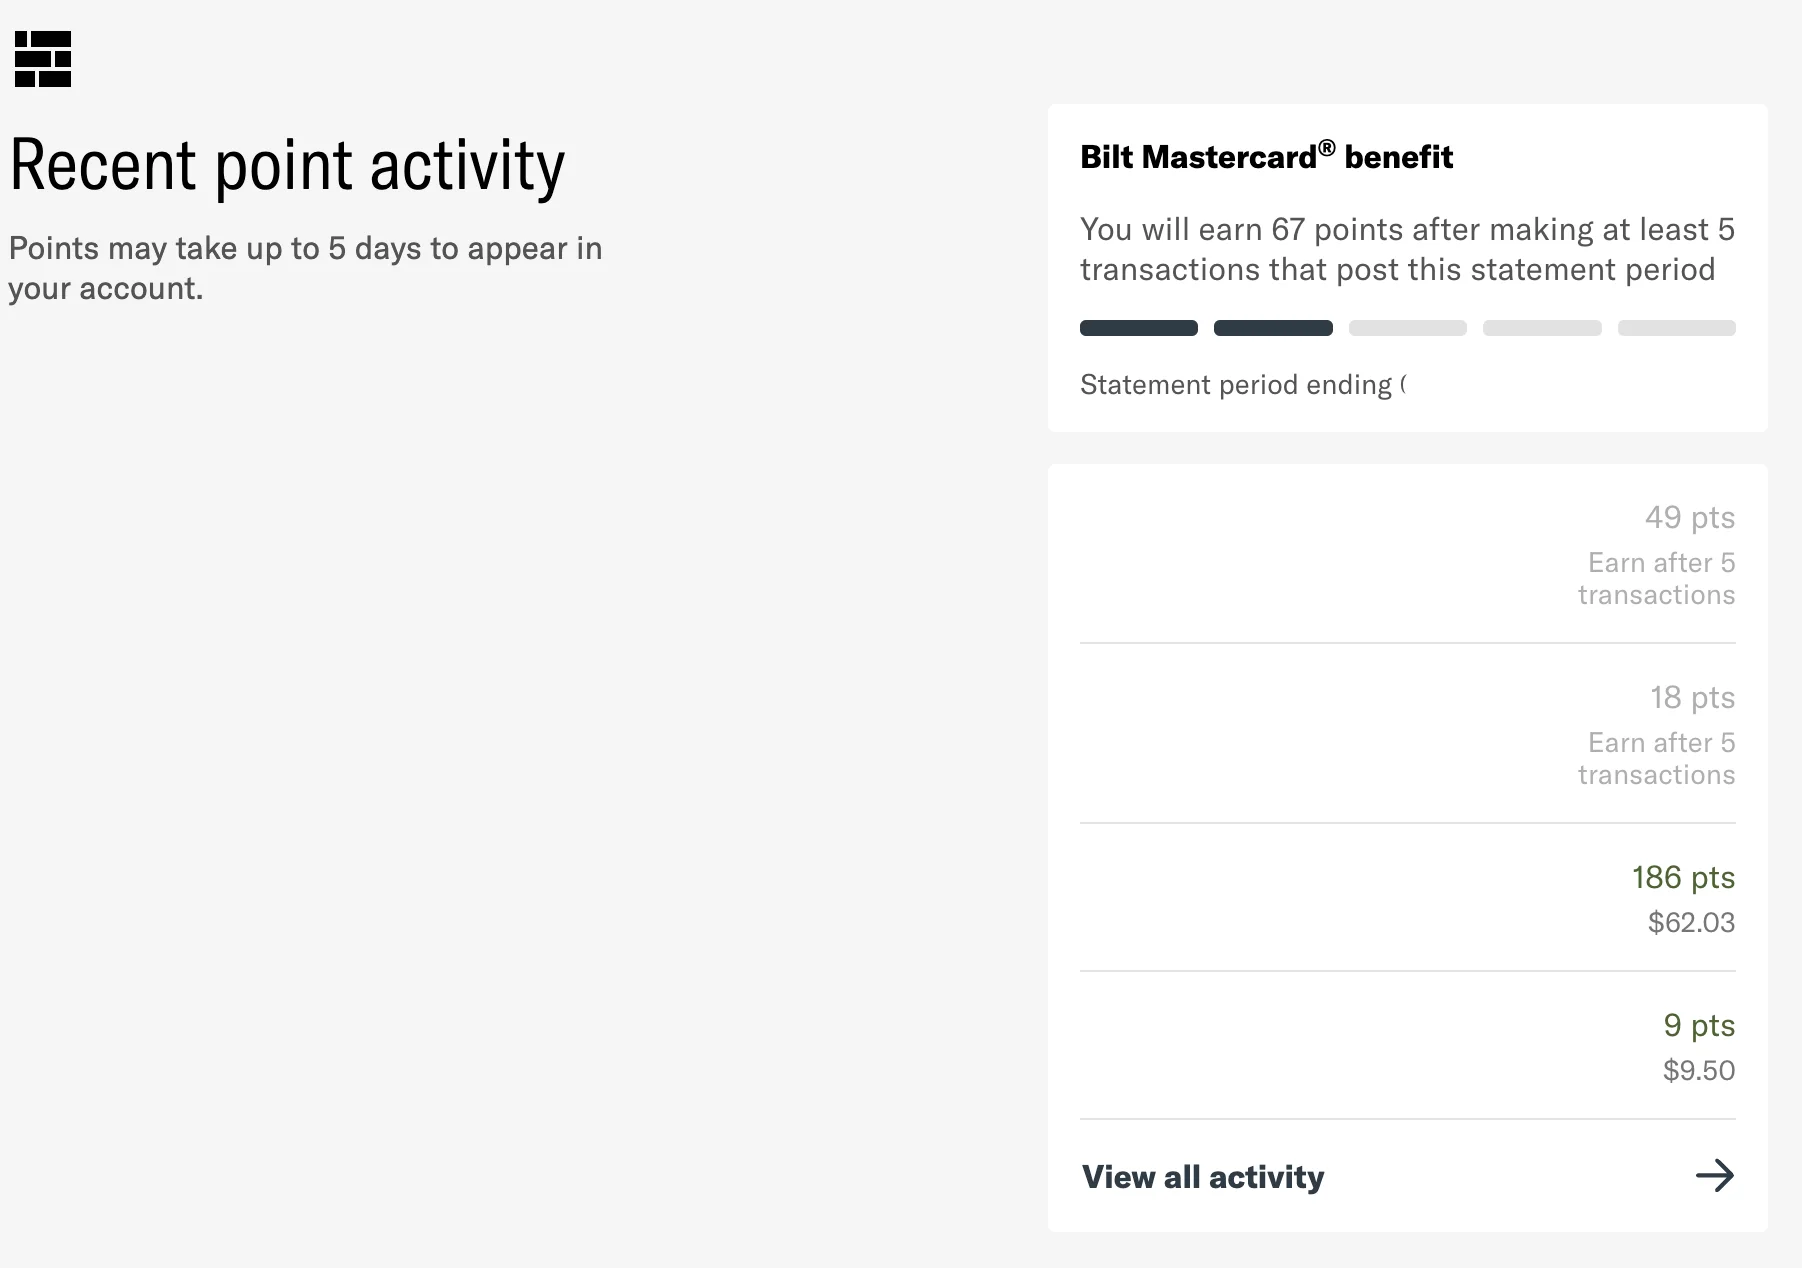
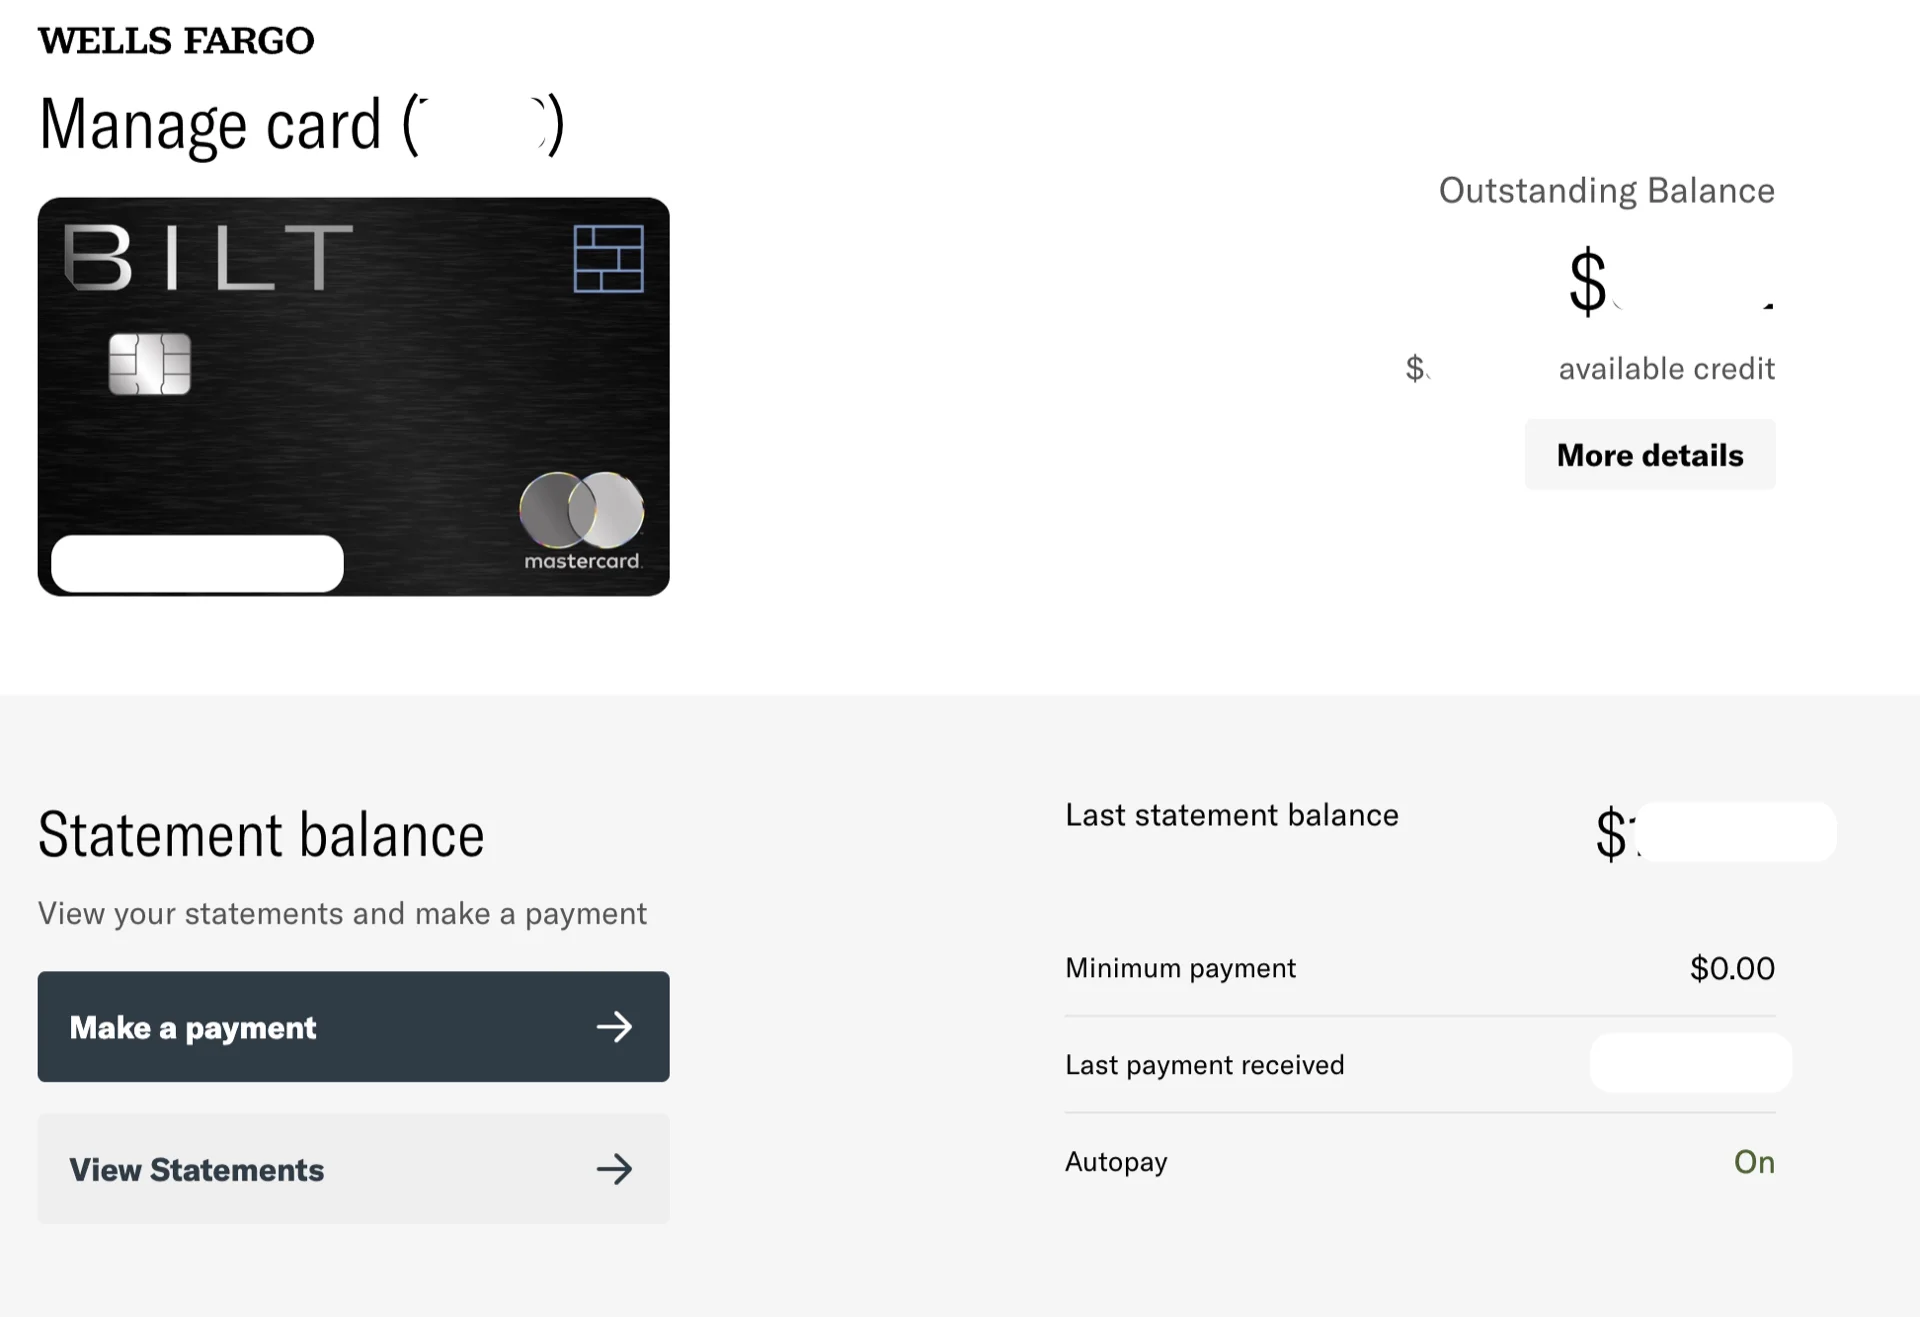
Using the Bilt rewards website, you can check the card balance, transaction details, manage your card payment, set up auto payment and do most things for your card.
Protection benefits and Travel benefits
The Bilt Cards are Mastercards, so Mastercard cardholder benefits apply. Since the Bilt Card 2.0 relaunch the card is no longer issued by Wells Fargo, so Bilt publishes its own benefits guide for each tier.
The full guide to benefits is published by Bilt for the Blue, Obsidian and Palladium cards. I list them below and encourage you to read through the fine print if you want to leverage these benefits. They are subject to change at any time, so giving you a direct source is better than summarizing them here.
Cellular Telephone Protection
This coverage reimburses You for the cost to repair or replace the Cell Phone in the event it is Damaged, Stolen, or is unrecoverable due to Involuntary and Accidental Parting. Cracked screens, cosmetic damage or scratches that do not impact the Cell Phone’s capabilities or functionality are not covered.
Mastercard ID Theft Protection
Mastercard ID Theft Protection alerts you to possible identity theft by monitoring the surface, dark and deep web, searching for compromised credentials and potentially damaging use of your registered personal information. It also provides you with resolution services should you find yourself a victim of identity theft.
Purchase security
If an item You purchase is damaged or stolen within the first ninety (90) days from the date of purchase, We may reimburse You the cost to repair or replace the item.
To be eligible for coverage, You must pay for the entire cost of the item with Your Covered Card and/or Bilt Rewards program associated with Your covered Account.
Auto Rental Collision Damage Waiver
This coverage reimburses You if a covered accident or theft occurs to the Rental Car.
To be eligible for coverage, the following must occur:
- You must pay for all of the cost to rent the car with Your Covered Card and/or Bilt Rewards program associated with Your Covered Card Account.
- You must decline the rental company’s collision loss/damage insurance.
Trip Cancellation and Interruption Protection
If a Trip is cancelled or interrupted for a covered reason (See What’s Covered), You may be reimbursed the cost of nonrefundable Common Carrier tickets.
The rest of the benefits are on the website provided above, so I will stop here.
FAQ about Bilt credit card
What do you need to qualify for a Bilt credit card?
Answer: Bilt does not publish a minimum credit score; approval is decided by its bank partner (Column N.A.) based on your full credit profile.
How hard is it to get the Bilt credit card?
Answer: There is no published minimum score. As with any card, a stronger credit profile helps, and Bilt says applying has no impact on your score unless approved.
Is Bilt owned by Wells Fargo?
Answer: No — and since the 2026 Bilt Card 2.0 relaunch, the card is not issued by Wells Fargo at all. Bilt is its own private company, founded in 2021, and the Bilt rewards program is managed by Bilt. The Bilt Cards are issued by Column N.A. and serviced by Cardless. (Wells Fargo issued the earlier Bilt Mastercard, which is where the confusion comes from.)
Can you use Bilt to pay rent?
Yes, you can. If you are a Bilt Alliance resident, you can pay rent directly using the mobile app or on the Bilt website.
If you live outside of the Bilt Alliance, you can still pay rent with the Bilt Rent account, which lets you pay landlords in existing portals by the automated clearing house or ACH. Bilt will give you a routing number and account number to pay rent, and you'll still earn points. Alternatively, if your landlord requires a check, then Bilt can mail a check to your landlord on your behalf.
How does Bilt send a check?
Checks are sent via USPS® First-Class Mail® and take 5 to 7 business days to deliver. You can learn more about mailing a rent check with Bilt here.
Does Bilt do a hard pull?
Yes. Applying for a Bilt Card means a hard pull from the issuer (Column N.A., serviced by Cardless) to evaluate your application.
How do I pay for my Bilt card?
There are multiple ways to pay your Bilt card balance. If you connect your bank account to Bilt, you can initiate the payment using the Bilt mobile app or website. Since the card is now serviced by Cardless, payments run through Bilt rather than the Wells Fargo app.
What credit bureau does Bilt credit card use?
Since the Bilt Cards are issued by Column N.A., that issuer pulls your credit history, and Bilt does not publish which bureau it uses. However, there is no harm in temporarily unfreezing your credit reports with all three credit bureaus when you apply for the card.
Bilt reports your rent payment to all three credit bureaus Experian, Equifax, and TransUnion.
Can I use my Bilt credit card anywhere?
Since the Bilt credit card is a Mastercard, you can use your Bilt credit card anywhere that Mastercard is accepted.
Can I pay my mortgage with Bilt credit card?
Yes, now you can. Under Bilt Card 2.0 you earn up to 1.25X points on eligible residential mortgage payments made through Bilt, with no annual cap and no transaction fee. Commercial mortgages are not supported.
How much is a Bilt point worth?
Bilt points are commonly valued at about 2.2 cents each — that is The Points Guy's valuation, which Bilt itself cites on its card page. The value varies by redemption method: transfers to airline and hotel partners (usually 1:1) tend to deliver the most.
What is better for my points: Bilt Travel portal or transfer partners?
The short answer is that it depends on the cash price of your ticket. Value a Bilt point at about 2.2 cents (The Points Guy's valuation), work out how many points the Bilt Travel Portal wants for the flight, then compare that with how many miles you would need via an airline partner. Most transfer partners stay at a 1:1 ratio.
Let me use an example:
- Say you want to fly from San Francisco to Orlando (Florida) in Jul
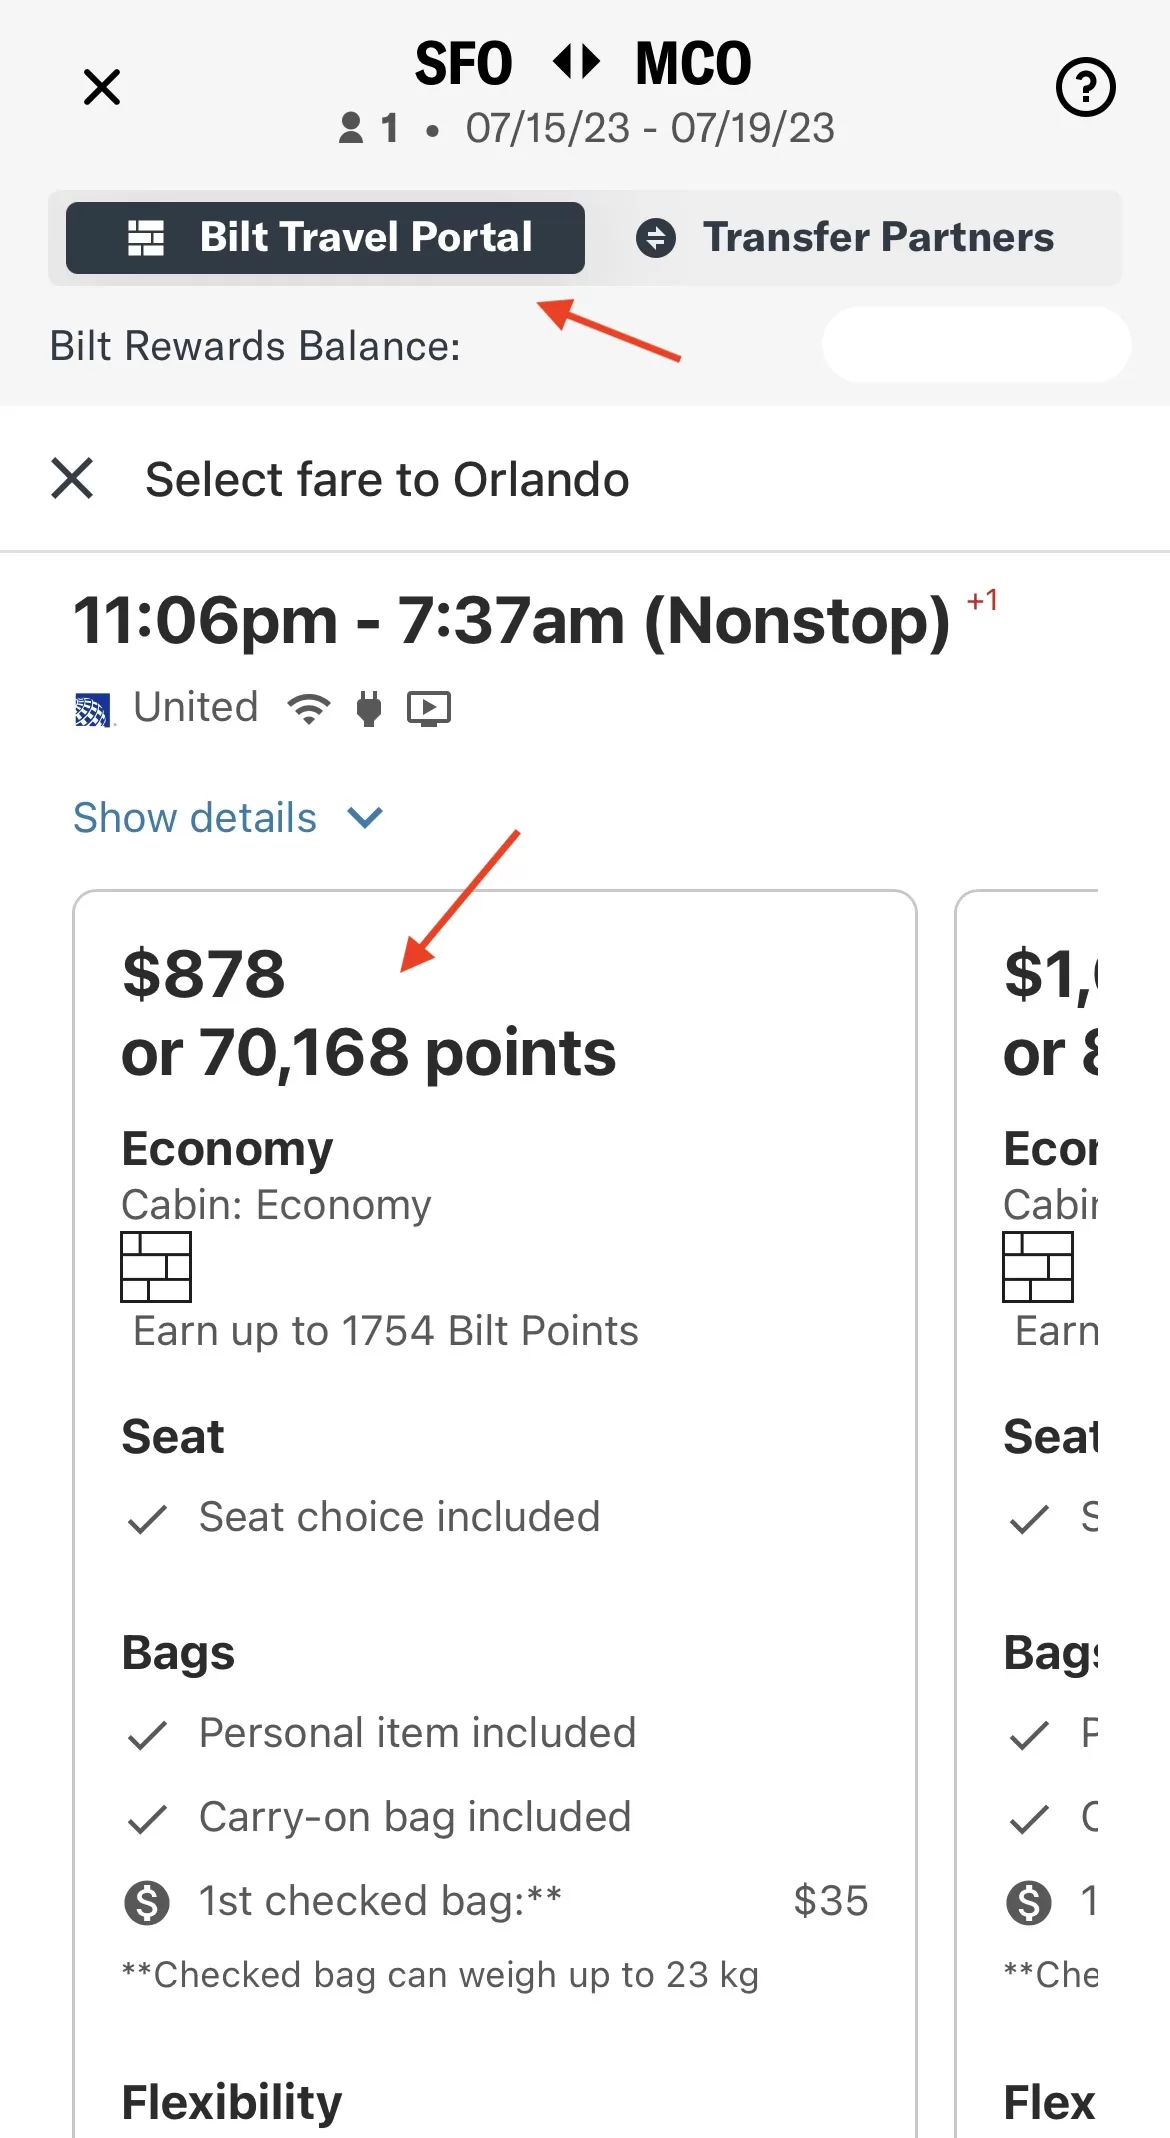
- Searching on the Bilt portal for a non-stop flight costs $878 or 70,168 Bilt points for a United return flight, economy ticket.
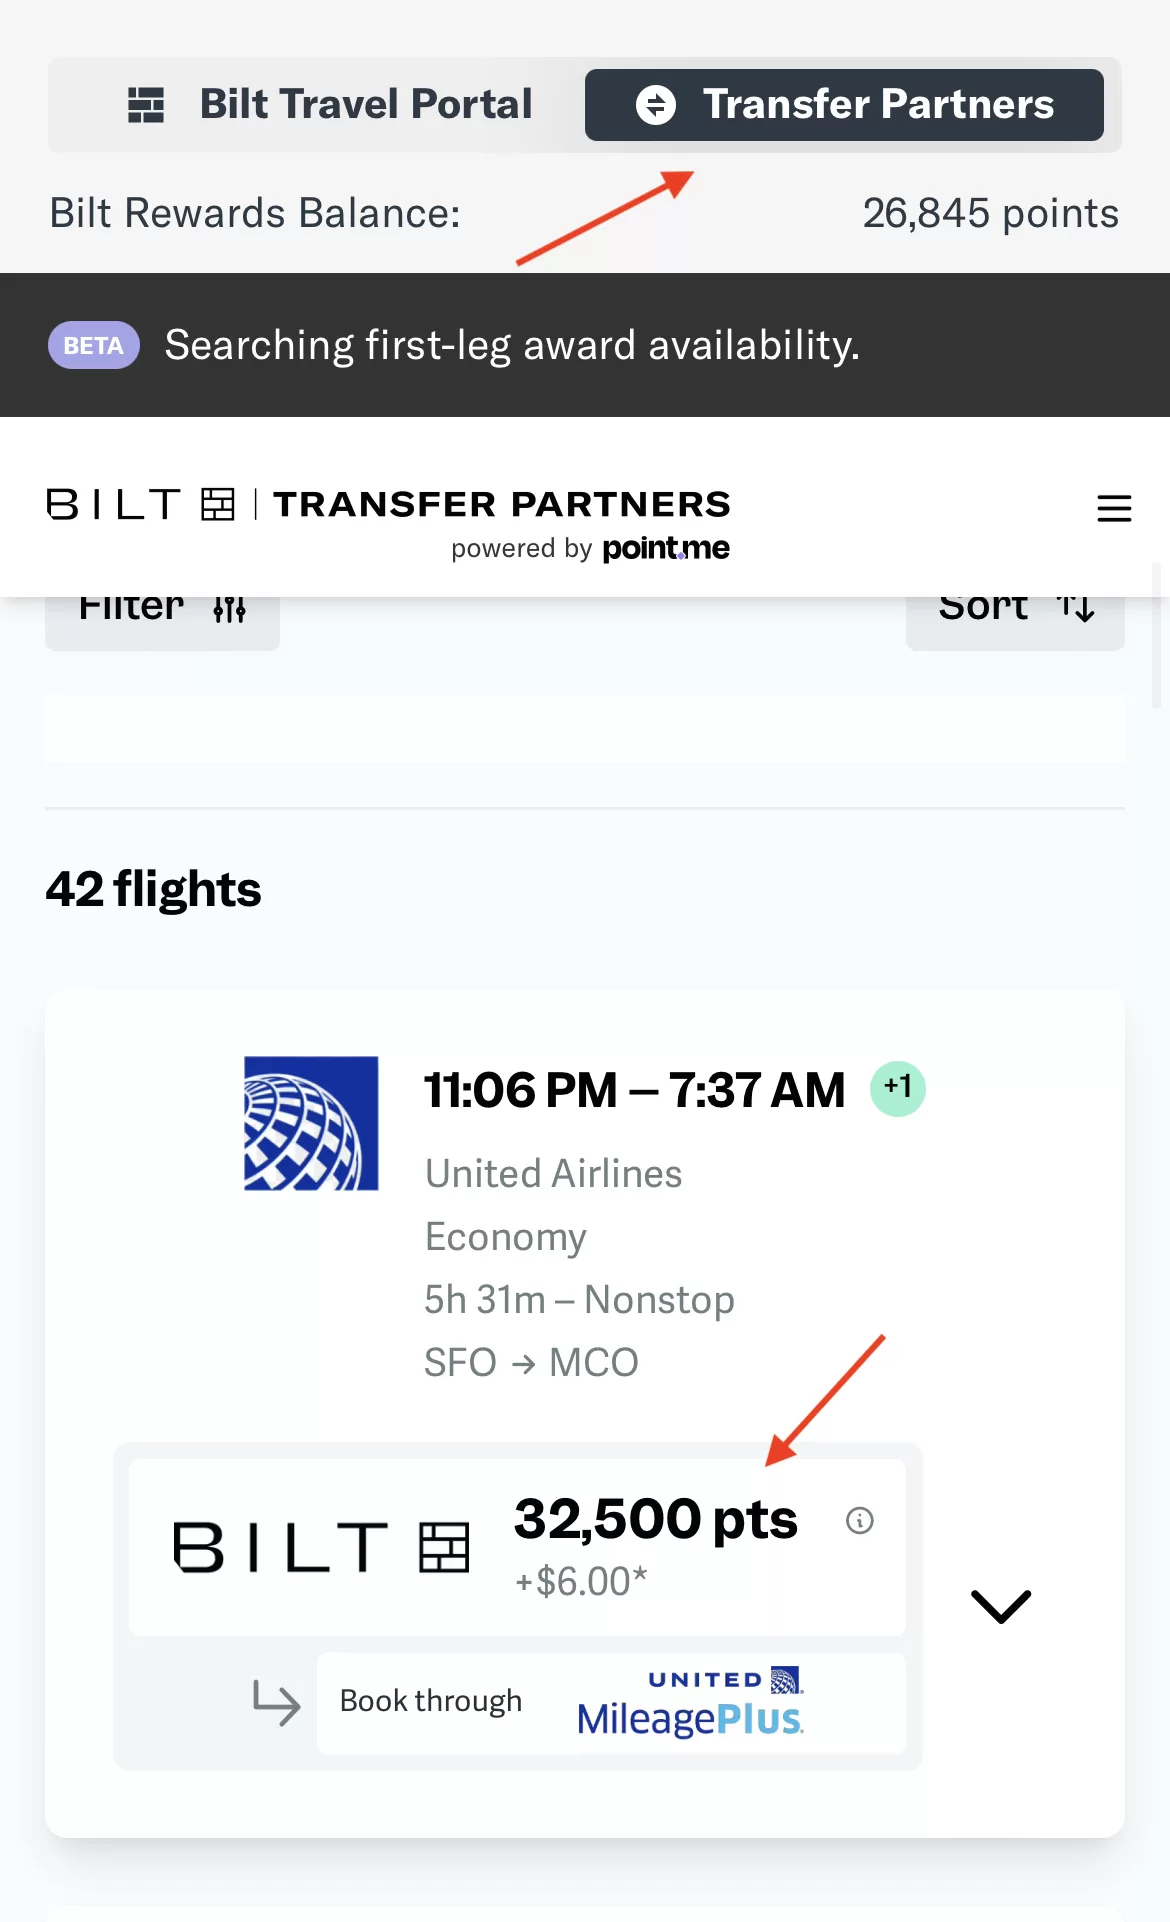
- Searching directly on United Airlines, it says that for the exact same flight, it costs about 32.5k miles.
- So in this case, it is much better to transfer Bilt points to United Airlines and then book directly on United.
By the way, in the Bilt travel portal, there is a search function via "transfer partner" too. Basically, you can see directly on the portal the miles/points needed between booking directly on Bilt or via the partner. It is very convenient.
Is the Bilt card metal?
Yes. The Bilt Cards are premium metal cards, and the Palladium tier offers a limited-edition mirror design.
Does Bilt report rent payments?
Yes. Bilt can report your rent payments to all three major credit bureaus (Experian, Transunion, Equifax) for free. Specifically, this is on Bilt's website "When renting at a Bilt Alliance property, you can choose to have your rent payments automatically reported by Bilt to the credit bureaus each month, which can help build your credit history with each on-time rent payment."
There you have it. I think Bilt is one of those rare products where the value proposition is genuinely clear — if you pay rent, you might as well earn points on it. Are you using Bilt already? Or do you have a different strategy for maximizing your rent payments? I'd love to hear what's working for you.
Cheers,
Chandler
P.S: If you think Bilt is suitable for you, you can use this link to the Bilt Cards to apply. And if you want to learn even more about the Bilt rewards program, check out the link.
Disclaimer: This is educational content, not advice. Nothing here is financial, investment, credit, tax, insurance, healthcare or legal advice, and nothing here is a recommendation to open, buy or use any product or account. Rates, limits, rules, fees and offers change frequently, and I am not a licensed adviser in any of these fields. Do your own research, verify the current figures and terms with the provider or the relevant authority (such as the IRS), and speak to a qualified professional before you act on anything you read here. Your circumstances may differ from the examples in this post.